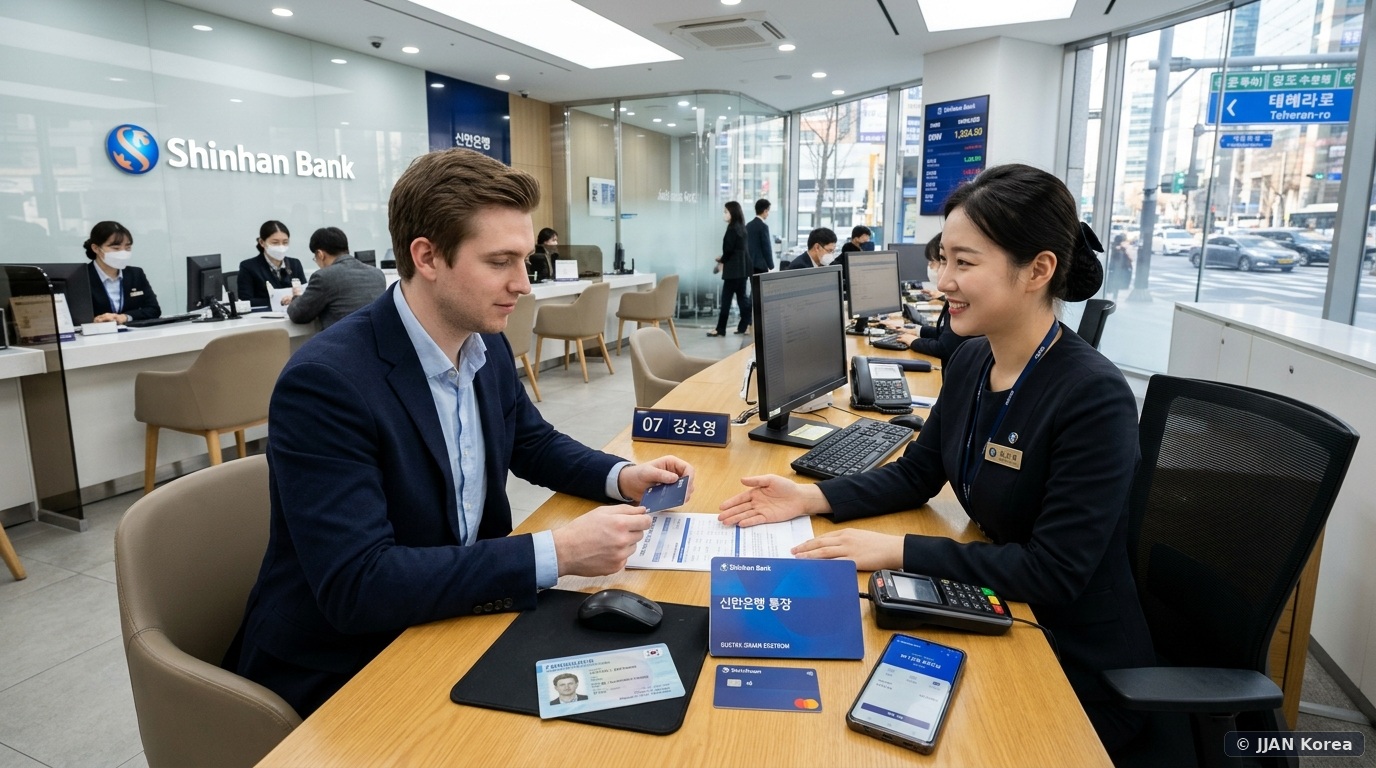

Establishing a tier-1 domestic bank account in South Korea is the ultimate logistical gateway to everyday independence. From receiving employment payroll and paying monthly apartment rent via automated clearing networks to unlocking seamless mobile payments through KakaoPay, Toss, and Naver Pay, living in Korea without a local debit card is an exercise in daily friction.
However, due to aggressive regulatory crackdowns by the Financial Supervisory Service (FSS) aimed at eradicating financial voice phishing syndicates and illegal “cannon accounts” (대포통장), Korean commercial banks enforce rigorous account opening barriers on foreign nationals. Walking into a random bank branch without proper proof-of-employment or tax verification will almost certainly result in instant rejection. This comprehensive guide outlines the exact document dossiers, top foreigner-friendly banks, strict initial transfer limits, and mobile banking activation procedures in 2026.
1. The Four Best Foreigner-Friendly Banks in Korea
While South Korea features dozens of commercial lenders, international residents should focus strictly on the top four commercial institutions maintaining dedicated foreigner desks:
| Bank Name | English App & Support Quality | Special Foreigner Services | Best Suited For |
|---|---|---|---|
| Hana Bank (하나은행) | Exceptional (Hana 1Q Global App) | Dedicated Global Branches open on Sundays (Itaewon, Ansan, Daelim); multi-language teller counters | #1 Top Recommendation for all expats, foreign workers, and newly arrived residents |
| Shinhan Bank (신한은행) | Very High (Shinhan SOL Global App) | Designated university campus partner branches; excellent foreign exchange remittance rates | International university students (D-2/D-4) and corporate professionals |
| Woori Bank (우리은행) | High (Woori WON Global) | Global financial centers across industrial zones; multi-lingual phone support hotline | Working professionals and long-term residents |
| KB Kookmin Bank (KB국민은행) | Moderate (KB Star Banking) | Largest physical branch and ATM footprint across South Korea | Residents living in regional cities and rural provinces |
2. Mandatory Document Dossier Checklist
Under FSS compliance guidelines, tellers cannot open an unrestricted bank account without verifying your legal identity and Purpose of Transaction (금융거래 목적확인서). You must physically present the following documents at the counter:
- Physical Alien Registration Card (ARC): The card must be unexpired and display your legal registered residential address. (Passports are only accepted for limited-tier tourist accounts that cannot access internet banking or debit cards). Ensure your card is in order with our complete Alien Registration Card (ARC) issuance guide.
- Original Physical Passport: Required to verify your international signature, nationality, and entry visa grant status.
- Proof of Employment / Activity Purpose:
- Salaried Employees: Certificate of Employment (재직증명서) issued within 30 days and an official Employment Contract (근로계약서).
- University Students: Certificate of Enrollment (재학증명서) issued within 14 days and student ID card.
- Self-Employed / Freelancers: Business Registration Certificate (사업자등록증) or service provision contracts.
- Signed Housing Lease Contract: Proves residency in the jurisdictional district of the bank branch. Review contract security rules in our Jeonse and Wolse housing deposit guide.
- Active Korean Smartphone Number: The mobile phone plan must be registered under your exact English name as printed on your ARC to pass real-time Carrier Identity Verification (통신사 본인확인).
3. The “Financial Limitation Account” (금융거래 한도제한계좌) Reality
When you successfully open a new account, the bank will initially classify your account as a Financial Transaction Limit Account (한도제한계좌). This anti-fraud status enforces rigid daily transfer ceilings:
- ATM Cash Withdrawal Limit: ₩300,000 per day
- ATM Electronic Transfer Limit: ₩300,000 per day
- Internet / Mobile Banking Transfer Limit: ₩300,000 to ₩1,000,000 per day
- In-Person Teller Counter Transfer Limit: ₩1,000,000 to ₩3,000,000 per day
How to Lift Transfer Limits to Normal Status
To upgrade your account to standard limits (e.g., ₩10,000,000 to ₩50,000,000 per day), you must return to the bank branch after establishing legitimate financial transaction history:
4. Setting Up Mobile Banking & Linking KakaoPay
South Korea operates virtually cashless. Once your physical Check Card (debit card) is issued at the branch counter, execute these digital setups immediately:
5. International Remittance Rules & FX Bank Designations
Under the Foreign Exchange Transactions Act (외국환거래법), foreign residents sending salary abroad must designate a single financial institution as their Primary Foreign Exchange Bank (외국환거래지정은행):
- Annual Remittance Ceiling Without Proof: You can wire up to $50,000 USD per calendar year abroad without presenting documentary proof of income.
- Wages Exceeding $50,000 USD: To remit amounts exceeding the $50,000 annual limit, visit your designated FX bank with your tax payment certificate and employment contract to prove the capital represents legitimate earned domestic income.
6. Frequently Asked Questions (FAQ)
Can I open a Korean bank account on a tourist visa with only a passport?
Technically, select branches of Hana Bank or Shinhan Bank can open a non-resident passport account for short-term tourists. However, these accounts are severely restricted: they issue no debit cards, have zero access to mobile internet banking, cannot send money transfers, and require physical teller visits for every cash withdrawal. Long-term residents should wait until their physical ARC is issued.
What is the difference between a Korean “Check Card” and a “Credit Card”?
A Check Card (체크카드) is an instant-debit card directly linked to your checking account balance; it carries zero credit risk and is issued immediately to foreigners at the teller counter. A Credit Card (신용카드) requires extensive credit screening, a high domestic credit score, permanent residency or long-term E-7 status, and minimum income documentation.
Why does my English name on mobile banking trigger an error during identity verification?
The single most common verification failure occurs because of formatting discrepancies. Your English name across your Bank Account, ARC, and Mobile Telecom Carrier must match character-for-character, including capitalization, spacing, and name order (e.g., LAST FIRST MIDDLE vs. FIRST LAST). If your telecom company entered your name without middle spaces, bank systems will reject the identity verification match.
Can foreigners open accounts with Korean online neo-banks (KakaoBank or Toss Bank)?
Currently, KakaoBank and Toss Bank permit foreigner account opening only for registered foreign residents holding a valid ARC and an unexpired mobile phone registered under their own name. However, in-person traditional banks (Hana, Shinhan) remain vastly superior for initial account opening due to foreign exchange compliance desk support.
🛡️ JJAN Korea Editorial Standards & Fact-Checking Verification
This article was independently researched, field-tested, and audited by the JJAN Korea Banking & Financial Compliance Desk in Seoul. Field-tested across foreigner-specialized branches of Hana Bank, Shinhan Bank, and Woori Bank; compliance rules audited against Financial Supervisory Service (FSS) guidelines.
Notice an unlisted policy change, fare update, or revised administrative rule? Help us keep our international community accurately informed: Submit a Correction to our Seoul Newsroom.